Review retirement priorities close to home in Dublin
The Dublin Link spans the Scioto River and connects the two sides of downtown. For someone planning to stay in Dublin through retirement, daily life can include time near the river, visits with family, and the routines built over years in the community. Good retirement income planning begins with the life you want to support here.
Silver Bay Insurance offers a local place to ask those questions at our Reflections Drive office. You may be considering an annuity for the first time, trying to understand a contract you own, or preparing for a change in retirement income. The review starts with your priorities rather than a particular carrier or rate.
Give each part of your savings a purpose
Separate the money needed for everyday expenses, a reserve for unexpected costs, and the funds intended for longer-term goals. Those purposes may call for different levels of access. An annuity comparison is more useful when you know which portion of savings you can consider committing and what it needs to accomplish.
Bring broad income and spending estimates, along with the questions you want answered. You may want predictable payments, a defined interest guarantee period, or clarity on the tradeoffs of a contract. We can help organize the discussion without assuming all of your savings belong in an annuity.
Compare fixed, MYGA, indexed, and income annuities
Annuities differ in how they credit interest, arrange payments, and handle access to money. This comparison is a starting point for a review, not a recommendation to buy a category or contract.
| Approach | Purpose to discuss | Key question |
|---|---|---|
| Fixed annuity or multi-year guaranteed annuity (MYGA) | Interest accumulation with a stated rate guarantee period. | How does the commitment fit the date when I may need these funds? |
| Fixed indexed annuity | Interest crediting using a formula linked to an index, without directly owning the index. | What limits apply to crediting and which provisions may change? |
| Income annuity | A selected payment arrangement purchased with a premium. | How do payment timing and survivor choices fit my household? |
| Optional income benefit | Income features on an eligible contract under specific conditions, sometimes with added cost. | Which amounts represent cash value and which calculate a benefit? |
Compare the actual Ohio contract, its issuing insurer, and written terms. Fixed annuities and fixed indexed annuities have different crediting approaches. An income illustration needs its own explanation of what is guaranteed and which conditions affect the payments.
Annuity contract terms to understand before choosing
A useful comparison includes how you can access money, when a commitment ends, and what happens if your plans change. Ask for the surrender schedule, withdrawal provisions, and any adjustment that could apply. Discuss optional benefits separately from the basic contract so their conditions and costs are clear.
For an income arrangement, include the needs of a surviving spouse and what access remains after payments begin. If flexibility is a priority, make that explicit at the appointment. A payment amount is only one part of the decision.
Bring an existing contract into the conversation
If you already own an annuity, bring the latest statement and any notice about a decision or renewal date. Write down what you want to understand: a value on the statement, the withdrawal rules, an income feature, or what happens after a guarantee period.
A review may clarify what you have without leading to a transaction. Compare keeping the current contract with any proposed change, including costs, restrictions, and benefits that could be lost or gained. Booking an appointment does not require transferring or replacing a contract.
Keep near-term needs separate from a long-term commitment
Home projects, family obligations, and a change in health or lifestyle can affect the funds you want available. Consider those priorities alongside regular spending. Knowing what needs to remain accessible helps keep the annuity conversation focused on money that has an appropriate time horizon.
Annuities are long-term insurance contracts. Early or excess withdrawals can trigger surrender charges or adjustments, and optional features may add costs. Guarantees depend on the issuing insurer’s claims-paying ability. Annuities are not FDIC-insured bank deposits. Discuss tax questions with a qualified tax professional before a transaction.
What to bring to your Dublin annuity review
Have your approximate retirement date, expected income sources, broad spending needs, and any current annuity statement ready. Tell us which decisions are urgent and which questions are still open. You do not need to select a carrier or product before meeting.
During the review, we can discuss the approaches relevant to your stated goal and identify the written terms that need comparison. If a specific contract is considered, request its actual provisions and illustration before deciding. Any proposed purchase or change is a separate decision.
Meet at our Dublin office or choose a remote appointment
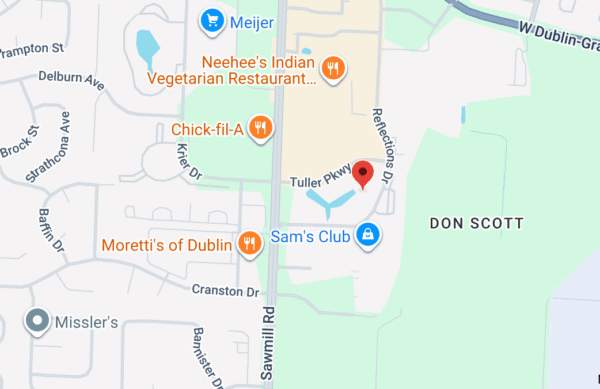
Our Ohio office is at 6479 Reflections Drive, Suite 230, Dublin, OH 43017. Office meetings are by appointment. Phone and video reviews are also available if you prefer to begin from home. Confirm the meeting format when you book so the appointment details match your choice. Meet our licensed agents to learn who will review your situation.
FAQs: Your Questions Answered
Yes. The introductory annuity review is complimentary and carries no obligation to buy or transfer funds. Any proposed product or transaction should be explained separately before you proceed.
No. Annuities are not FDIC-insured bank deposits. Guarantees depend on the issuing insurer’s ability to pay claims, and withdrawal restrictions depend on the contract.
Not necessarily. Some contracts use separate figures to calculate benefits. Ask the agent to identify which values can be withdrawn and which determine payments, using the actual contract.
No. Understanding or keeping the contract may be the appropriate next step. Compare any proposed change with the current provisions, including costs and benefits, before deciding.
Access and payment features depend on the contract. Ask which withdrawals are permitted, what charges may apply, and what access remains under a proposed income choice. The answer requires reviewing the specific arrangement.
Compare surrender periods, withdrawal rules, optional benefit costs, payment timing, survivor features, and the issuing insurer’s financial strength. A higher advertised rate does not show how a contract works when you need income or cash.
A multi-year guaranteed annuity (MYGA) is a fixed annuity with a guaranteed interest rate for a set period of years. Compare the length of the guarantee, surrender charges for early withdrawals, and what happens when the period ends.
They use different interest-crediting methods. A fixed-rate guarantee differs from a formula linked to an index. Compare the actual contract terms, limits, and time periods rather than assuming the categories work alike.
Bring broad income and spending estimates, your expected retirement timing, and any contract statement or notice you want reviewed. A short list of questions can help focus the conversation.
Yes. Office meetings are by appointment at 6479 Reflections Drive, Suite 230, Dublin, OH 43017. Phone and video reviews are available as alternatives. Confirm your preferred format when booking.