Start with your Columbus retirement budget
Columbus is Ohio’s capital, and the Scioto Mile connects downtown parks along the Scioto River. If you plan to spend retirement in Central Ohio, start with the life you want to support here: household bills, home maintenance, time with family, travel, and a reserve for unexpected expenses. Good retirement income planning turns those priorities into an income discussion before it turns them into a product decision.
List the monthly income you expect from Social Security, any pension, and other sources, then compare it with the spending you want that income to cover. An annuity may be worth exploring for a specific income gap, a longer-term savings goal, or a concern about income lasting. It should not be chosen simply because an advertised rate looks appealing.
Coordinate your pension and retirement savings first
For a Columbus household with a pension, the monthly payment is only part of the picture. Survivor choices, retirement timing, and a spouse’s needs can change the income available later. For someone with employer retirement savings, the account balance and the money needed in the next few years are separate questions.
Bring benefit estimates and any existing annuity statements. We can help organize the annuity comparison around your stated goals. A consultation does not require transferring a pension, rolling over an account, replacing a contract, or buying a product. Any proposed change deserves its own review of costs, benefits, and alternatives.
Compare fixed, MYGA, indexed, and income annuities
Different annuities solve different problems. The table below is a starting point for your appointment, not a recommendation to buy a particular contract.
| Approach | Purpose to discuss | Key question |
|---|---|---|
| Fixed annuity or multi-year guaranteed annuity (MYGA) | Accumulation with a specified interest guarantee for a defined period. | How long can I commit the money, and what happens when the rate period ends? |
| Fixed indexed annuity | Interest crediting determined by a formula linked to an index; it is not a direct investment in that index. | How do caps, participation rates, spreads, and renewal terms affect crediting? |
| Income annuity | Converts a premium into payments for a set period or a lifetime, depending on the option chosen. | When do payments begin, and what happens after one spouse dies? |
| Optional income benefit | Income features on an eligible contract, sometimes for an added cost. | What conditions apply, what does it cost, and how does income differ from cash value? |
Compare the contract’s actual provisions, the issuing insurer, and products available in Ohio. Categories alone do not tell you how much income a specific contract would pay or whether its terms fit your circumstances.
Match the review to your next decision
If retirement is approaching, focus the appointment on your intended retirement date and the period between your last paycheck and the income sources that follow. If you are already retired, consider whether dependable income or continued access to savings is the more pressing concern. If a CD or existing annuity is nearing the end of a term, compare the next decision before allowing a deadline to drive it.
For couples, include both people’s priorities. One spouse may want predictable payments while the other wants funds available for family needs. We can discuss those tradeoffs and identify which contract questions need written answers before proceeding.
Annuity tradeoffs to understand before committing savings
An annuity is a long-term insurance contract. Depending on its terms, early or excess withdrawals may trigger surrender charges or a market value adjustment. Optional benefits can add costs. Certain payment choices limit later access to the premium. Guarantees depend on the issuing insurer’s claims-paying ability; annuities are not FDIC-insured bank deposits.
Keep an appropriate cash reserve outside any long-term commitment. Ask how a proposed contract handles withdrawals, beneficiary payments, inflation concerns, and changes in your household. If the money comes from a retirement account or a taxable account, discuss tax consequences with a qualified tax professional before making a transaction.
What to bring to your Columbus annuity review
A useful first conversation begins with your expected retirement date, sources of monthly income, broad spending needs, and the money you may need soon. Bring any current annuity statement or benefit estimate you want to discuss. You do not need to choose a carrier or know the name of a product before booking.
During the review, we will ask what you want the money to accomplish, explain relevant annuity approaches, and identify the details that should be compared. If further review is appropriate, request written terms and illustrations for the actual contract under consideration rather than relying on a general description.
 Serving Columbus from our Dublin office
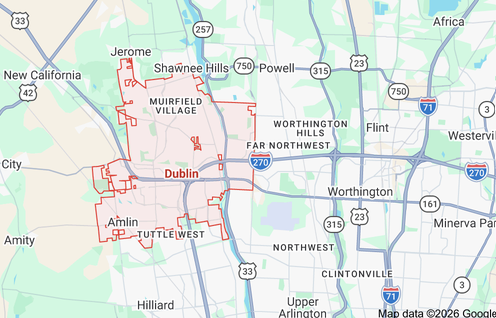
Silver Bay Insurance serves Columbus residents through phone and video appointments and through its Dublin office at 6479 Reflections Drive, Suite 230, Dublin, OH 43017. Office meetings are by appointment, so ask about availability when you book. Remote meetings let you begin the conversation without a drive across Central Ohio. Meet our licensed agents to learn who will review your situation.
FAQs: Your Questions Answered
The introductory annuity and retirement review is complimentary, with no obligation to buy. We should explain any product costs or later service arrangements separately before you proceed.
Yes. Columbus residents can book phone and video appointments. If you prefer an office meeting, ask about an appointment at our Dublin office at 6479 Reflections Drive, Suite 230, Dublin, OH 43017.
Yes. Bring your statement and contract details. A review can help you understand the current terms; it does not mean you should replace the contract. Compare any change with keeping what you already have.
Yes, the contract can limit access. Early or excess withdrawals may involve surrender charges or adjustments, and some income arrangements restrict access to the premium. Discuss emergency reserves and likely spending before committing funds.
Compare surrender periods, withdrawal rules, optional benefit costs, payment timing, survivor features, and the issuing insurer’s financial strength. A higher advertised rate does not show how a contract works when you need income or cash.
A multi-year guaranteed annuity (MYGA) is a fixed annuity that credits a guaranteed interest rate for a set number of years. Early withdrawals may trigger surrender charges, so compare the guarantee period, what happens when it ends, and whether you need access to cash.
Compare the crediting method first. A fixed annuity credits a stated interest rate for a set period, while a fixed indexed annuity credits interest using an index-linked formula with limits such as caps or participation rates. Then compare charges and withdrawal rules.
No. An annuity is an insurance contract, while a CD is a bank deposit, and annuities are not FDIC-insured. Compare access to money, guarantees, contract duration, and tax treatment instead of comparing rates alone.
Not necessarily. A pension may already cover the need an annuity would address. Review its income and survivor features, your other resources, and any remaining gap before considering an annuity.
Yes, an annuity may supplement other income if the contract fits your needs. Start with your existing income sources and household budget. The right type, amount, and timing depend on your situation.